What Counts as Income for ACA Subsidies (MAGI Explained)
The Marketplace does not ask for your salary, your bank balance, or your total earnings. It asks for a specific tax figure called Modified Adjusted Gross Income, shortened to MAGI, and it compares that figure with the federal poverty level for your household size. If you get MAGI wrong, you get the subsidy wrong, and the error only shows up at tax time. Fortunately, for most people MAGI is simple, because it is almost the same as a number already on their tax return.
MAGI in one paragraph
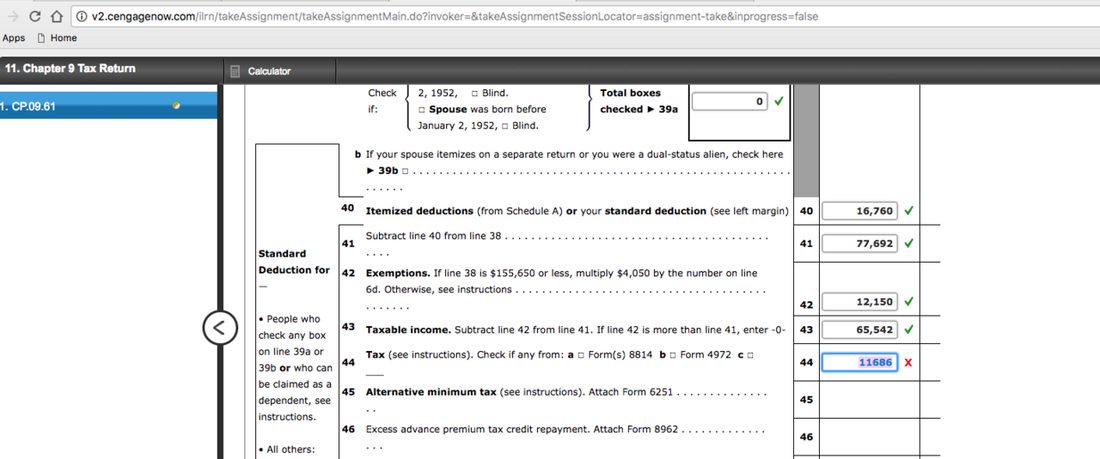
For premium tax credit purposes, MAGI equals your adjusted gross income, the number on line 11 of Form 1040, plus three specific add-backs: tax-exempt interest, the non-taxable portion of your Social Security benefits, and any foreign earned income you excluded under the foreign earned income exclusion. For most people who live in the United States, earn domestic income, and hold no municipal bonds, MAGI and adjusted gross income are identical. The add-backs exist to stop people from looking poorer than they are by sheltering income in otherwise non-taxable categories.
What counts, and what does not
| Counts toward MAGI | Does not count (in general) |
|---|---|
| Wages, salaries, tips, and net self-employment income | Qualified distributions from a Roth account, already taxed |
| Unemployment compensation, in full | Child support received |
| Social Security benefits, including the non-taxable portion (added back) | Gifts and inheritances |
| Capital gains, dividends, and interest, including tax-exempt interest (added back) | Supplemental Security Income benefits |
| Taxable retirement distributions from traditional IRAs, 401(k) plans, and pensions | Veterans' disability payments |
| Rental income and royalties, after expenses | Workers' compensation payments |
Two items deserve emphasis because they surprise people. First, unemployment benefits count in full, which can push a household over a threshold in a year when work was scarce. Second, a Roth withdrawal that is qualified does not count, because the tax was already paid on the contributions, while a traditional retirement withdrawal does count, because it enters adjusted gross income. The timing of a retirement withdrawal can therefore matter as much as its size, a point to discuss with a tax professional before, not after, the withdrawal.
Household MAGI, not just your MAGI
The Marketplace combines the MAGI of every household member who is required to file a tax return into a single household figure. A spouse's income counts, and a dependent child's income counts if that child is required to file. That is why a household can lose a credit when a spouse returns to work, even though the applicant's own pay did not change. It is also why the application asks about everyone in the tax household, not just the person buying the plan.
Worked examples (illustrative, not subsidy calculations)
Example 1: a single freelancer. Maya earns 52,000 dollars in net self-employment income, pays 3,000 dollars in deductible self-employment tax, and holds no municipal bonds and receives no Social Security. Her adjusted gross income is about 49,000 dollars, and with no add-backs her MAGI is also about 49,000 dollars. For 2026 coverage, that sits inside the 100% to 400% range for a single person, about 15,650 to 62,600 dollars, so she is in the range for a premium tax credit, subject to the other eligibility rules. Her actual credit would depend on the benchmark plan in her area and her age.
Example 2: a family near the cliff. A family of four has a MAGI of about 125,000 dollars. For 2026 coverage, that sits just inside the family-of-four range, about 32,150 to 128,600 dollars, so a credit is possible. If a year-end bonus of 5,000 dollars pushes their MAGI to 130,000 dollars, they cross the 400% line, and under the restored rules their premium tax credit drops to zero for that year, with reconciliation at tax time. The lesson is not to fear a bonus. It is to estimate honestly, report changes promptly, and understand that a small income change near the cliff can have an outsized effect.
Example 3: a retiree with mixed income. A retired couple receives Social Security, part of which is non-taxable, holds municipal bonds paying tax-exempt interest, and takes a traditional IRA distribution. Their adjusted gross income includes the taxable Social Security portion and the IRA distribution, but not the tax-exempt interest or the non-taxable Social Security portion. For MAGI, both of those are added back. A couple that looks comfortably under a threshold on adjusted gross income alone can be over it on MAGI, which is exactly why the add-backs exist.
Sources: HealthCare.gov, Modified Adjusted Gross Income glossary and income pages; Internal Revenue Service, Modified Adjusted Gross Income guidance; 26 U.S.C. section 36B (premium tax credit MAGI definition).